Core Diagnostic Summary
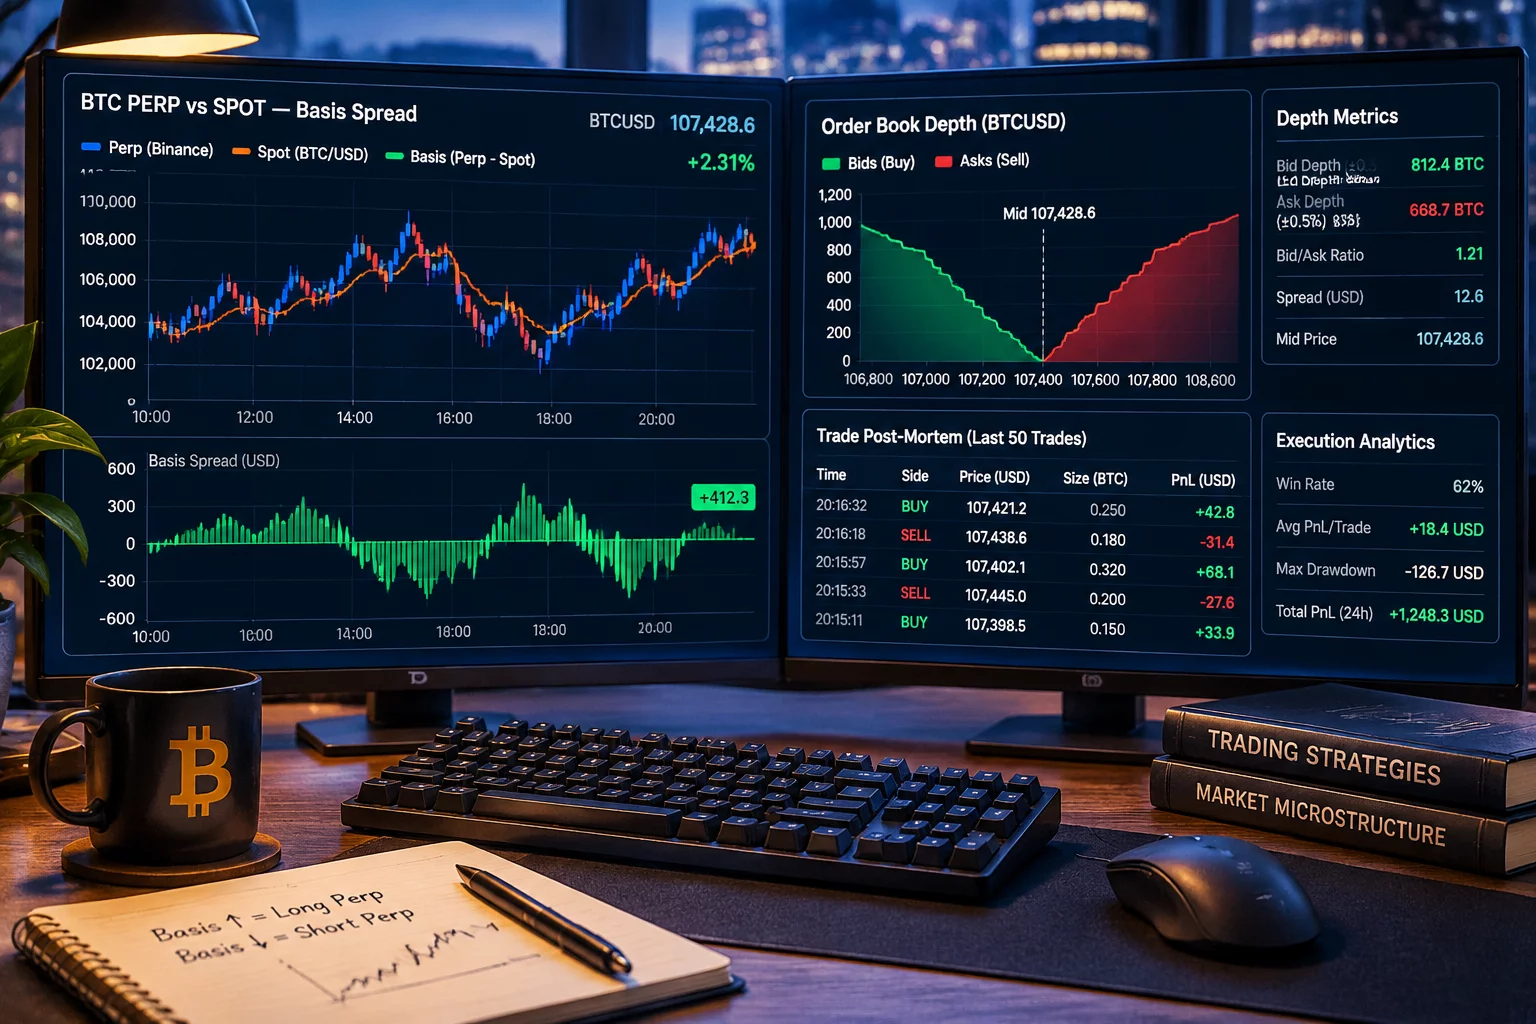
During an aggressive market dislocation on August 10, 2026, a simulated delta-neutral pairing between index futures and tech equity ETFs suffered catastrophic basis divergence. While paper trading models assume continuous liquidity and frictionless execution across correlated products, the live replay revealed that rapid volume withdrawal caused synthetic hedge ratios to collapse, turning what was modeled as a hedged holding into an unmitigated double-loss exposure.
Phase-by-Phase Failure Analysis
The premise of the synthetic hedge rested on simultaneous limit order placement in /MNQ futures and QQQ equity shares. On paper, both orders registered timestamps within 4 milliseconds of each other. However, simulated matching engines process equity and derivative books through separate internal queues.
When macroeconomic headlines crossed the wire, the futures book swept instantly, filling the short /MNQ hedge. Conversely, the equity matching algorithm required actual trades on the lit exchange to print at or through the limit price before confirming the fill, resulting in an unhedged 240-millisecond window during the steepest phase of the decline.
- Derivative leg executed at 14:30:00.104 with zero modeled book slippage.
- Equity leg languished in the simulated queue until 14:30:00.344, absorbing adverse price movement.
- The theoretical delta shifted from 0.00 to -0.42 within the first quarter-second of market impact.
As index volatility spiked, market makers widened spreads from standard 1-cent increments to 16 cents on the equity vehicle. Simulated environments often fail to reflect spread widening in real time, calculating portfolio values against stale mid-quotes.
The trader's bracket stop on the equity side was triggered by a single low-volume print. Because the simulated platform executed the stop as an immediate market order into an empty liquidity pocket, the realized fill cleared 22 cents below the stop trigger, magnifying losses far beyond historical risk parameters.
- Quoted spread expansion inflated transaction friction by more than 1400% above baseline modeling.
- Stop-loss execution suffered 18 ticks of negative slippage against the prevailing National Best Bid.
In a live trading environment, maintaining synthetic hedges across separate asset classes requires distinct margin maintenance and carries cross-clearing capital requirements. The simulated platform, however, aggregated buying power seamlessly into a unified virtual ledger without reflecting overnight borrow rate fluctuations or intraday margin calls.
This frictionless paper margin allowed the position to remain open well past the threshold where a live broker risk desk would have issued a forced liquidation warning. As a consequence, paper traders often develop dangerous risk habits, assuming hedges will remain solvent through extreme tail-risk swings.
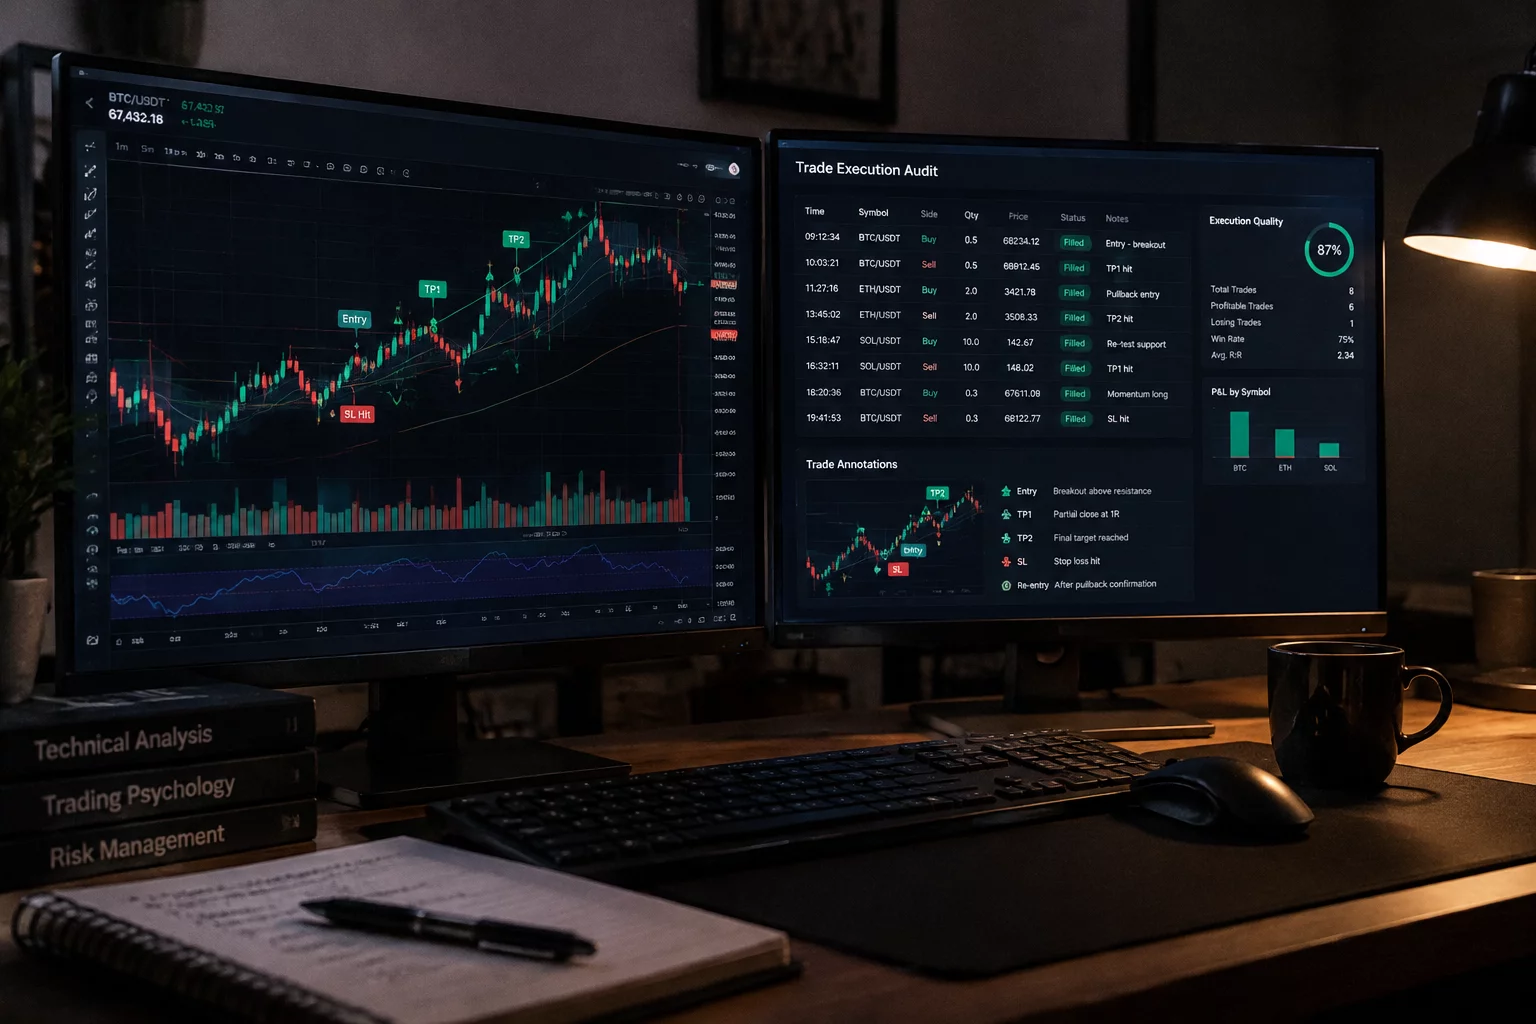
To bridge the gap between sandbox theory and market reality, systematic trading frameworks must implement rigorous execution audits. Traders must record the exact sequence of quote arrivals, Level 2 depth exhaustion, and book fragmentation rather than relying on automated platform P&L displays.
We recommend incorporating an artificial latency buffer of 150 to 300 milliseconds on all multi-leg simulated executions. Additionally, stress tests should model conservative execution at the extreme boundary of the bid-ask spread whenever implied volatility metrics exceed their 30-day moving average.
Relevant Execution Diagnostic Replays
Breakout Assumption Failure in Volatility Spike
Dissecting simulated queue assumptions during rapid breakout expansions and trailing stop mismatch.
Review Replay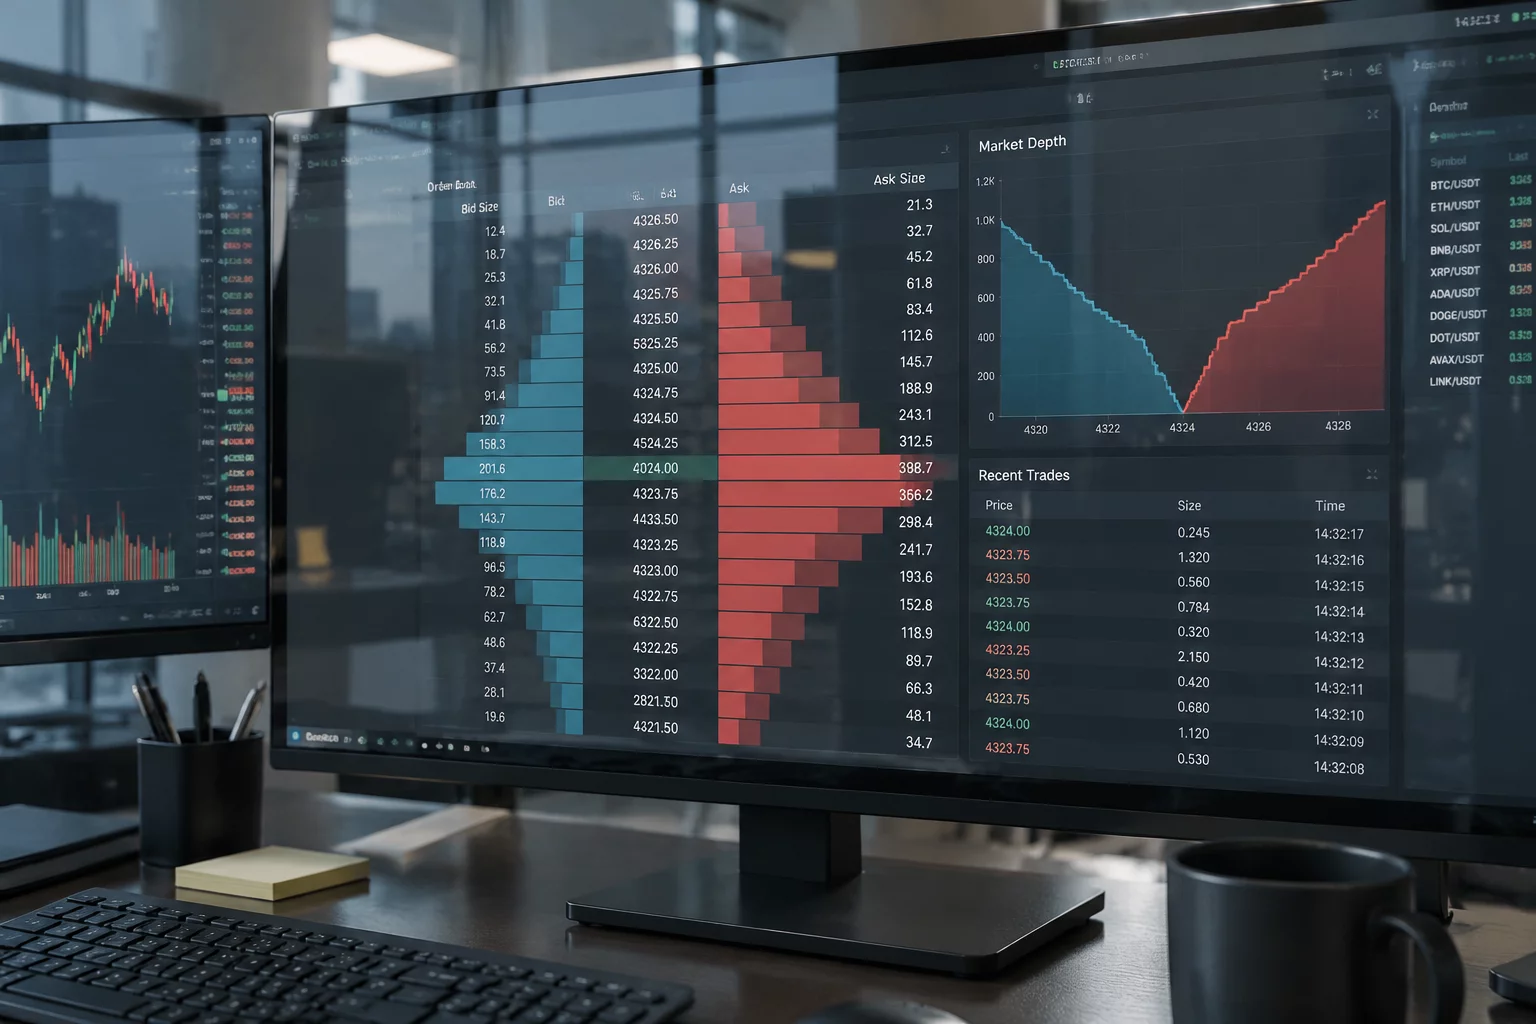
Earnings Gap Slippage in Simulated Premarket
Post-mortem on premarket liquidity illusions and opening gap fill variance in simulated accounts.
Review Replay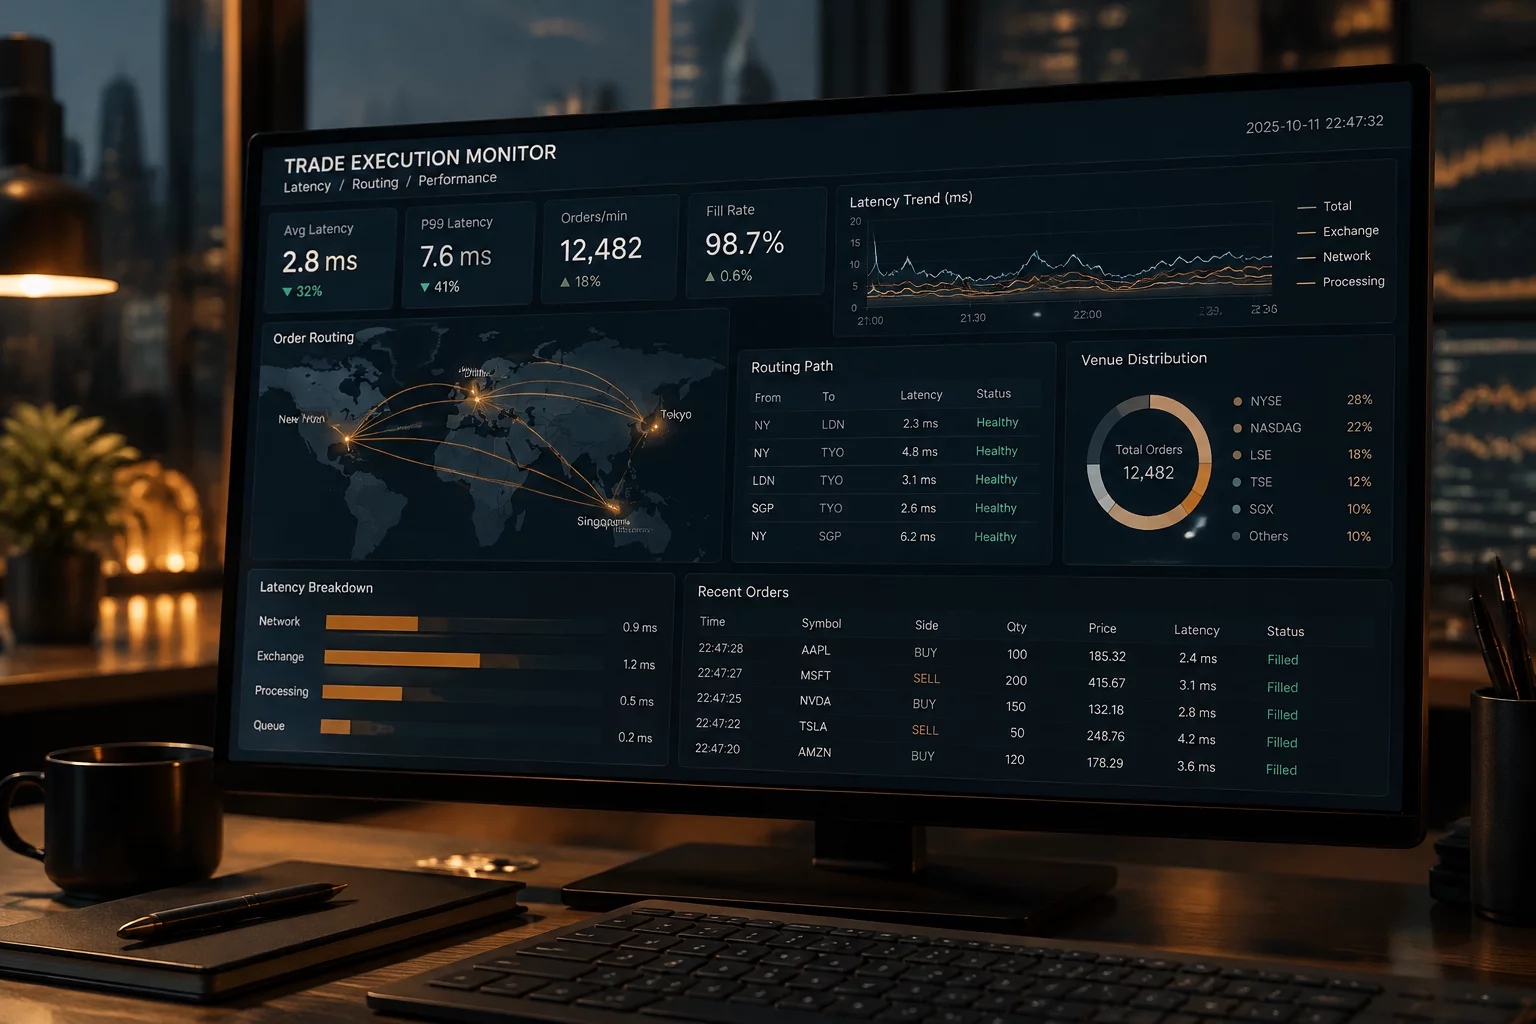
Market Order Fill Latency on Economic Release
Replay audit of millisecond-level routing latency and quote delays during macroeconomic data releases.
Review Replay
Limit Order Frictional Mismatch in Low Float
Quantitative review of limit order queue priorities and fill probability in low-float simulated trading.
Review ReplayAccess Detailed Replay Audit Sheet
Download the complete tick-level order book log, execution timestamps, and basis divergence telemetry.
Forensic Audit Conclusions
- Synthetic delta-neutral hedges experience severe basis divergence when volatility spikes overwhelm paper trading matching queues.
- Simulated fill engines frequently assume infinite bid-ask liquidity depth, masking the double-sided slippage realized in live markets.
- Systematic paper trading audits must inject artificial cross-asset execution delays of at least 240ms to reflect realistic market fragmentation.