Execution Environment & Release Parameters
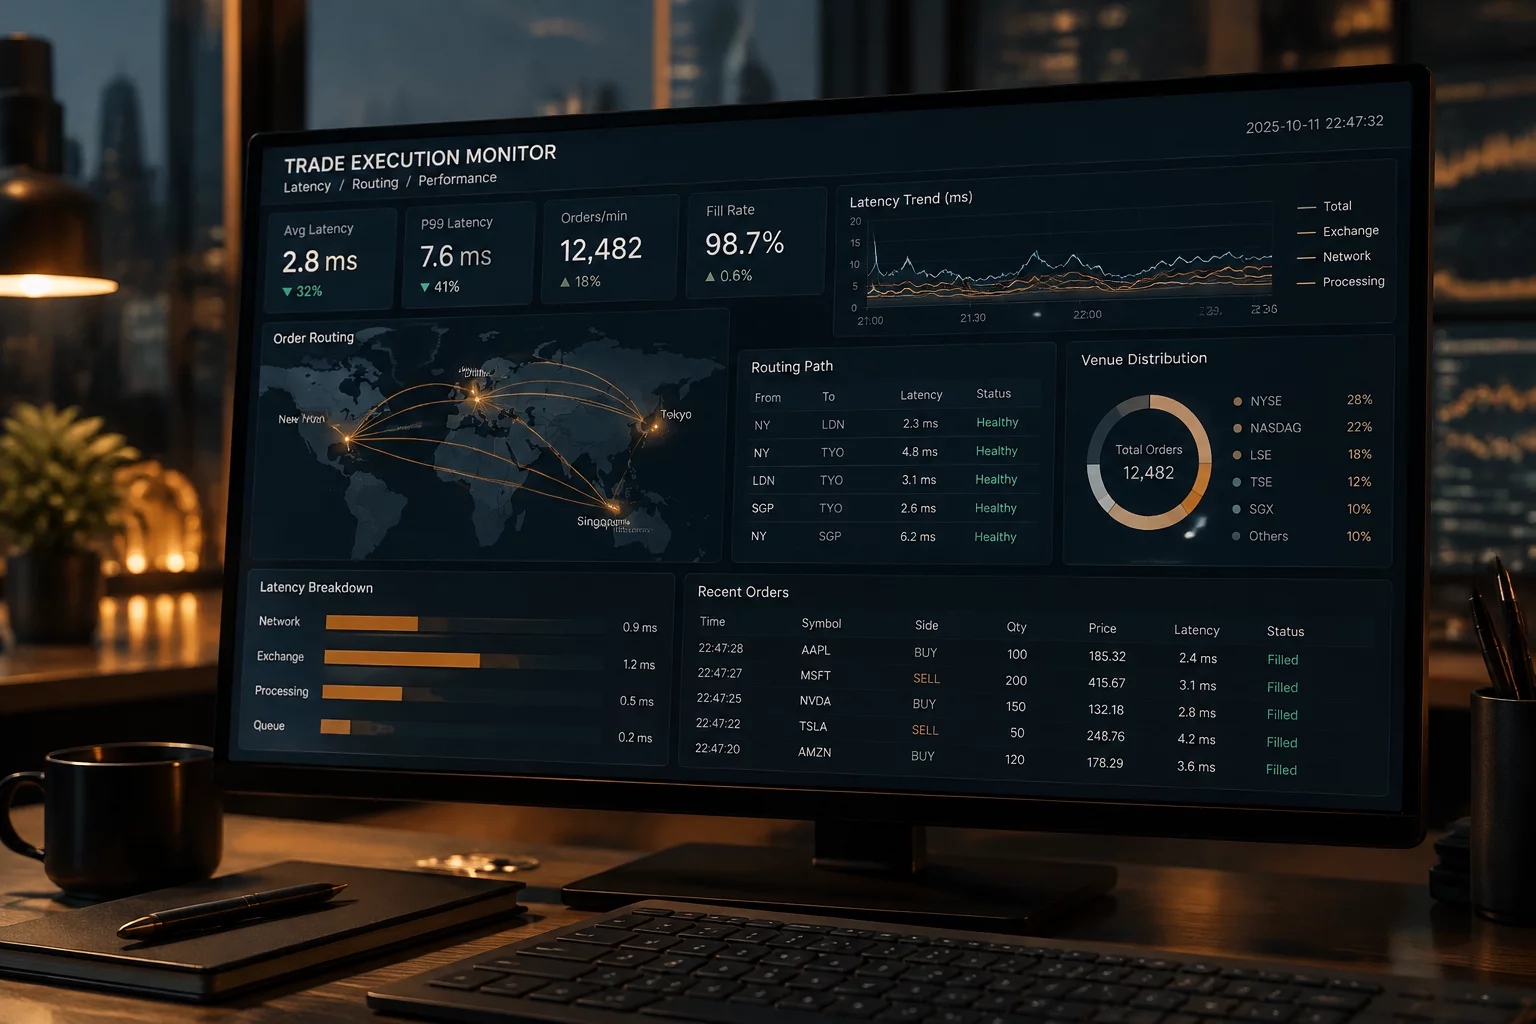
When major macroeconomic data hits the tape, market depth collapses and order books reprice within single-digit milliseconds. In retail simulation environments, market orders frequently execute against phantom liquidity at the last quoted inside bid or ask, masking catastrophic live execution friction. This post-mortem reviews a simulated trade placed directly into the 08:30 AM Non-Farm Payrolls (NFP) print, contrasting the paper fill against real-time Level 2 book transitions and matching engine queues.
Comprehensive Execution Breakdown
At exactly 08:30:00 EST, the Bureau of Labor Statistics released employment figures that significantly deviated from consensus estimates. Operating in a simulated desktop platform, the trader initiated an immediate breakout market order to buy 5 contracts at 08:30:00.320, expecting rapid upside momentum.
The simulation sandbox returned a complete execution confirmation within 12 milliseconds at 5,842.25. However, reconstructed historical time-and-sales data confirms that no institutional resting volume existed at that price band past 08:30:00.080, exposing an artificial fill artifact.
- Simulated Fill Timestamp: 08:30:00.332 EST at 5,842.25
- Actual Composite Best Offer at 08:30:00.332 EST: 5,847.00
- Theoretical Friction Understatement: 19 ticks ($237.50 per contract)
During high-impact economic prints, liquidity providers widen quotes and temporarily withdraw passive limit orders from the top of book to mitigate adverse selection. In live market conditions, an incoming market order sweeps through multiple sparse price tiers or experiences matching engine queuing delays.
The simulated execution engine evaluated the order against stale Level 1 cache data rather than simulating queue seniority or multi-tier order consumption. This created an illusion of clean liquidity depth where real execution would have incurred severe partial fills.
- Simulated Book Assumption: Infinite depth at single inside ask
- Live Market Reality: 4 consecutive price levels swept across 80 milliseconds
The discrepancy between simulated fills and actual queue outcomes fundamentally distorts risk-reward models. A trade planned with an initial risk budget of 3 points ($150 per contract) incurred a live execution gap that exceeded the intended stop loss distance before the position was even acknowledged.
Paper trading records reflected an immediate unrealized gain of 2.50 points as prices surged. In a live trading account, the exact same entry order would have originated in an immediate unrealized drawdown of 2.25 points due to spread gap slippage.
To eliminate paper trading bias during economic catalysts, trading journals must apply post-trade friction penalties. Analysts should cross-reference fill timestamps against tick-by-tick aggregated tape data and apply a dynamic spread penalty corresponding to peak 1-second volatility.
Furthermore, systematic traders should restrict market order usage during scheduled Tier-1 macroeconomic announcements, favoring calibrated limit orders with strict price offsets to prevent catastrophic slippage.
Related Execution Case Studies
Breakout Assumption Failure in Volatility Spike
Evaluating how unexpected volatility expansions invalidate conventional range breakout entry rules in paper portfolios.
Review Replay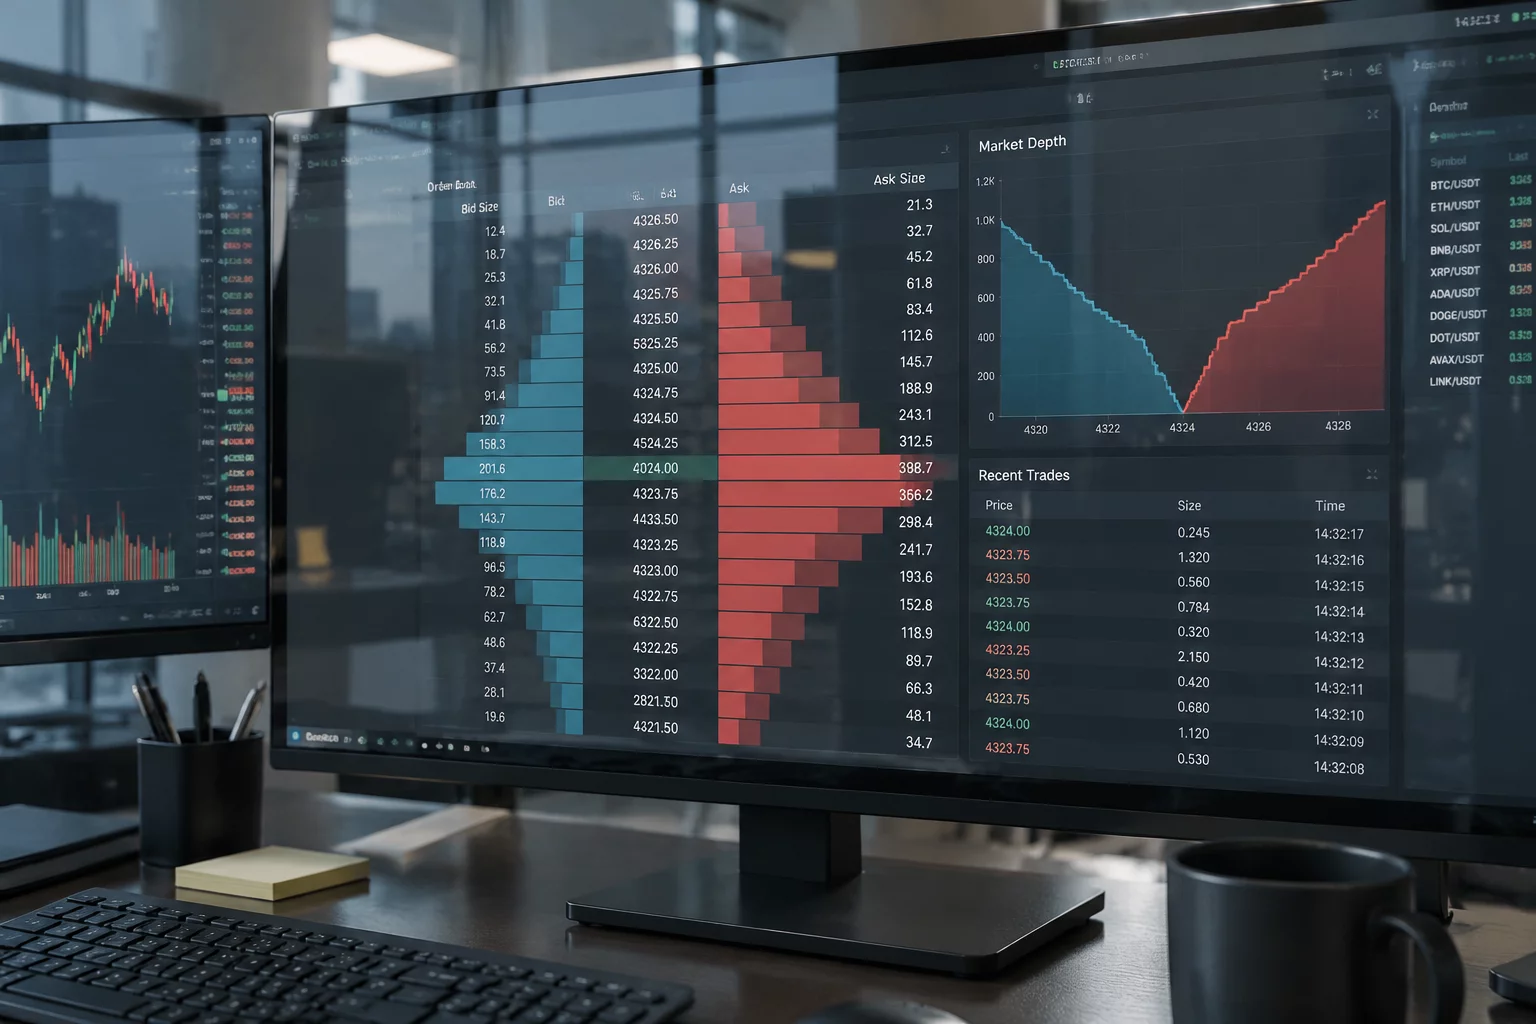
Earnings Gap Slippage in Simulated Premarket
Investigating thin premarket order book depth and massive spread slippage after high-profile earnings releases.
Review Replay
Limit Order Frictional Mismatch in Low Float
Analyzing simulated limit queue fills versus actual queue priority and partial execution rates in low float stocks.
Review Replay
Bracket Liquidity Illusion in Overnight Session
Dissecting automated bracket stop fills during illiquid overnight hours and real-world stop run gaps.
Review ReplayAudit Your Own Execution Discrepancies
Access systematic trade review templates and post-mortem frameworks calibrated for paper trading diagnostics.
Key Diagnostic Takeaways
- Simulated fills on macroeconomic releases consistently fail to model queue priority and book thinning, providing artificially favorable prices.
- Market orders executed during high-impact prints experience extreme live spread blowouts that standard paper engines routinely ignore.
- Always adjust simulated post-trade journal entries by applying realistic historical tick spread penalties to maintain authentic expectancy.