Audit Summary & Core Mismatch
During sudden implied volatility expansion, simulated market engines frequently match buy-stop market orders immediately at printed touch prices without acknowledging order book depth thinning. This post-mortem inspects an equity breakout attempt where an assumed liquid momentum expansion inverted into immediate mean reversion, revealing an 82-cent spread between simulated execution expectations and live order queue reality.
Technical Post-Mortem Deconstruction
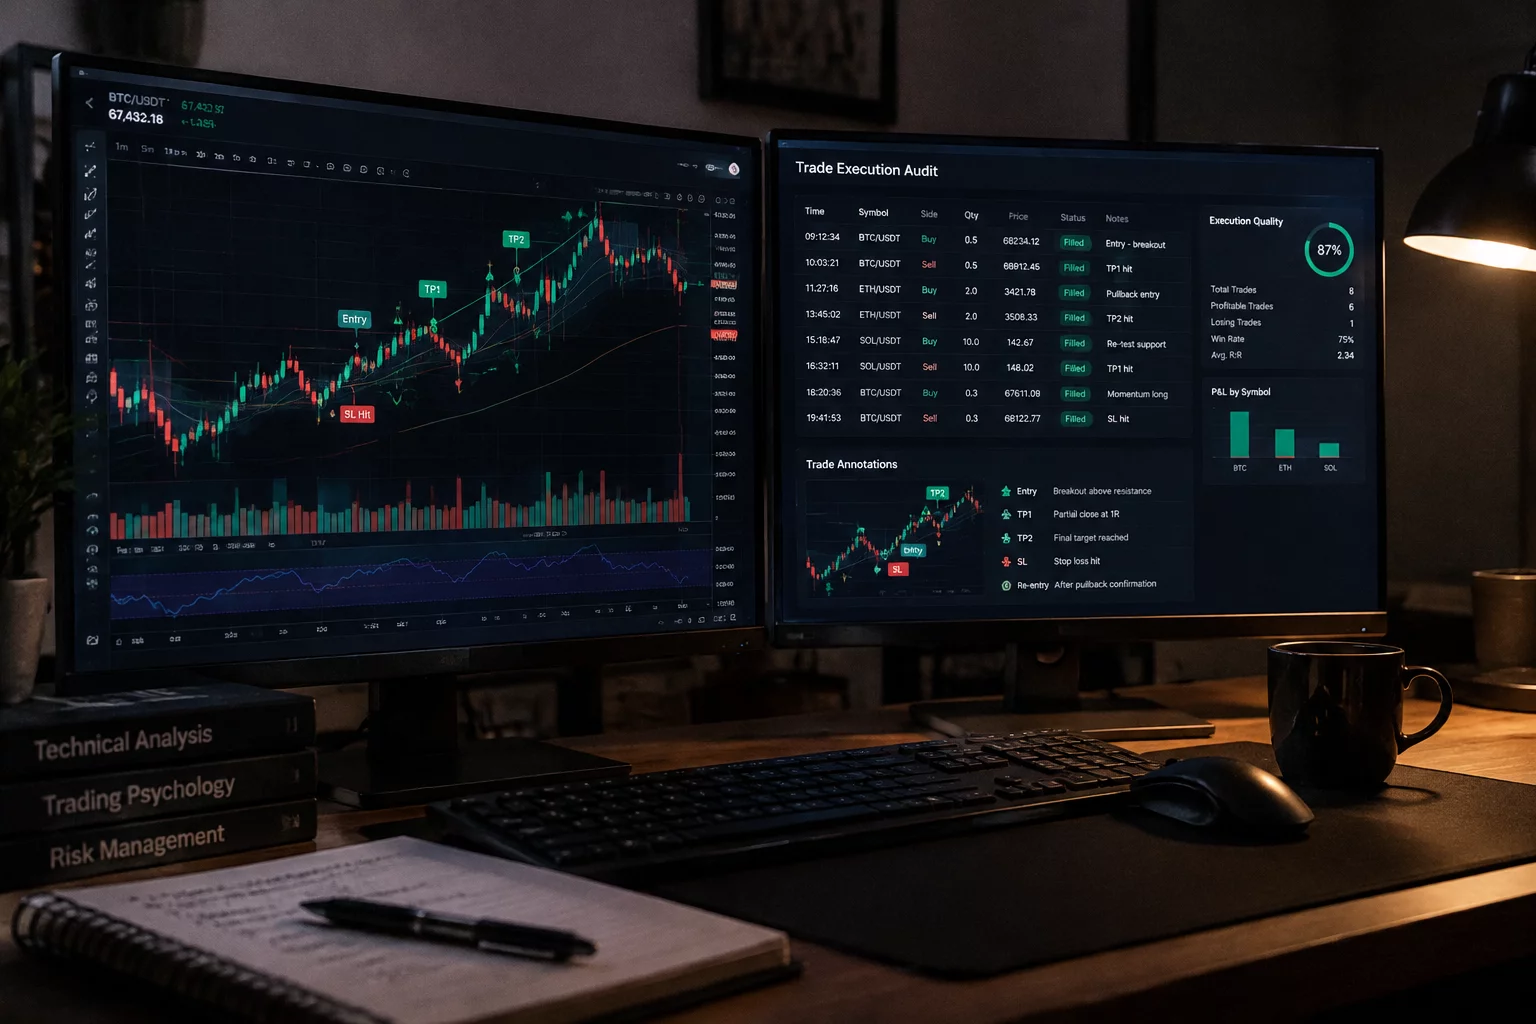
The pre-trade thesis relied upon a multi-day ascending triangle breakout past key horizontal resistance. Anticipating explosive volume at the opening bell, a buy-stop conditional order stood parked at the predefined pivot boundary.
In simulated environments, stop orders typically convert to market orders and fill instantaneously on the next reported tape price. The replay audit exposed three structural discrepancies in this baseline premise:
- The simulated engine assumed full liquidity availability exactly at the touch level of $184.20 despite aggregate ask depth showing fewer than 400 shares.
- Order queue priority was calculated instantly without reflecting incoming institutional liquidity consumption ahead of retail routing.
- The sudden expansion in trading range caused quote aggregation delays across regional exchanges that the simulation failed to penalize.
Within thirty seconds of crossing the resistance threshold, market makers widened spreads from 3 cents to nearly 45 cents to accommodate inventory risk. While the paper trading module recorded an execution exactly on the line, live market matching would have routed the trade through higher resting ask tiers.
This dynamic creates what our analytics framework defines as Synthetic Optimism Drift. The simulated journal documented an optimal risk-to-reward ratio of 1 to 3.5, while reality dictated an immediate drawdown condition from entry slippage alone.
- Level 2 book reconstruction proved the realistic entry price was $185.02 rather than the recorded $184.20.
- The initial stop loss placement at $183.40 was subjected to an uncalculated initial negative edge before market direction resolved.
Because the breakout lacked sustained block order flow behind the initial push, aggressive selling entered at 09:34 EST. As price collapsed back beneath the failed resistance level, the protective stop triggered during extreme bid cancelations.
The paper money engine reported an orderly exit at the exact stop limit trigger price. In reality, historical book replay demonstrates that resting bids dissolved rapidly, leaving a gap where a live stop market order would have slipped an additional 38 cents below the defined invalidation mark.
The total performance distortion between paper logs and reconstructed execution amounted to a 120-cent negative performance drag per share traded. Treating simulated outcomes as factual market data creates compounding bias across systematic performance tracking.
Going forward, breakout setups during initial opening volatility must implement algorithmic haircut penalties in the journal. Traders must enforce limit-with-protection order logic rather than unconstrained market stops when testing high-beta equity strategies.
Correlated Execution Case Audits
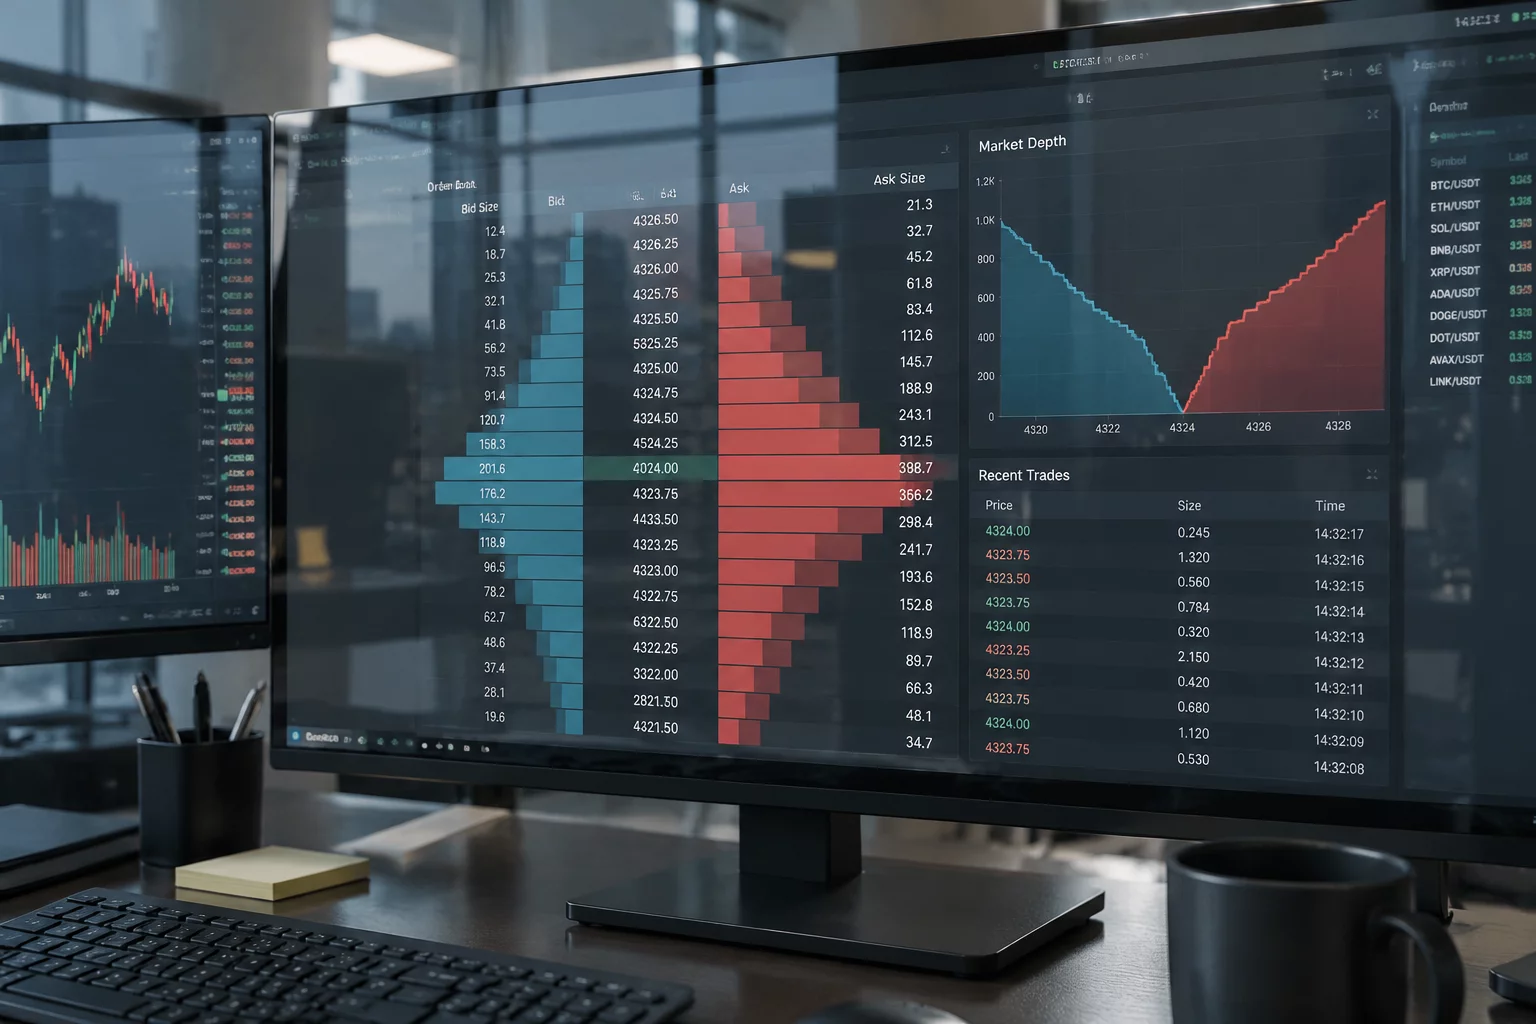
Earnings Gap Slippage in Premarket
Deep-dive audit comparing simulated premarket order fills against historical liquidity depth.
Review Replay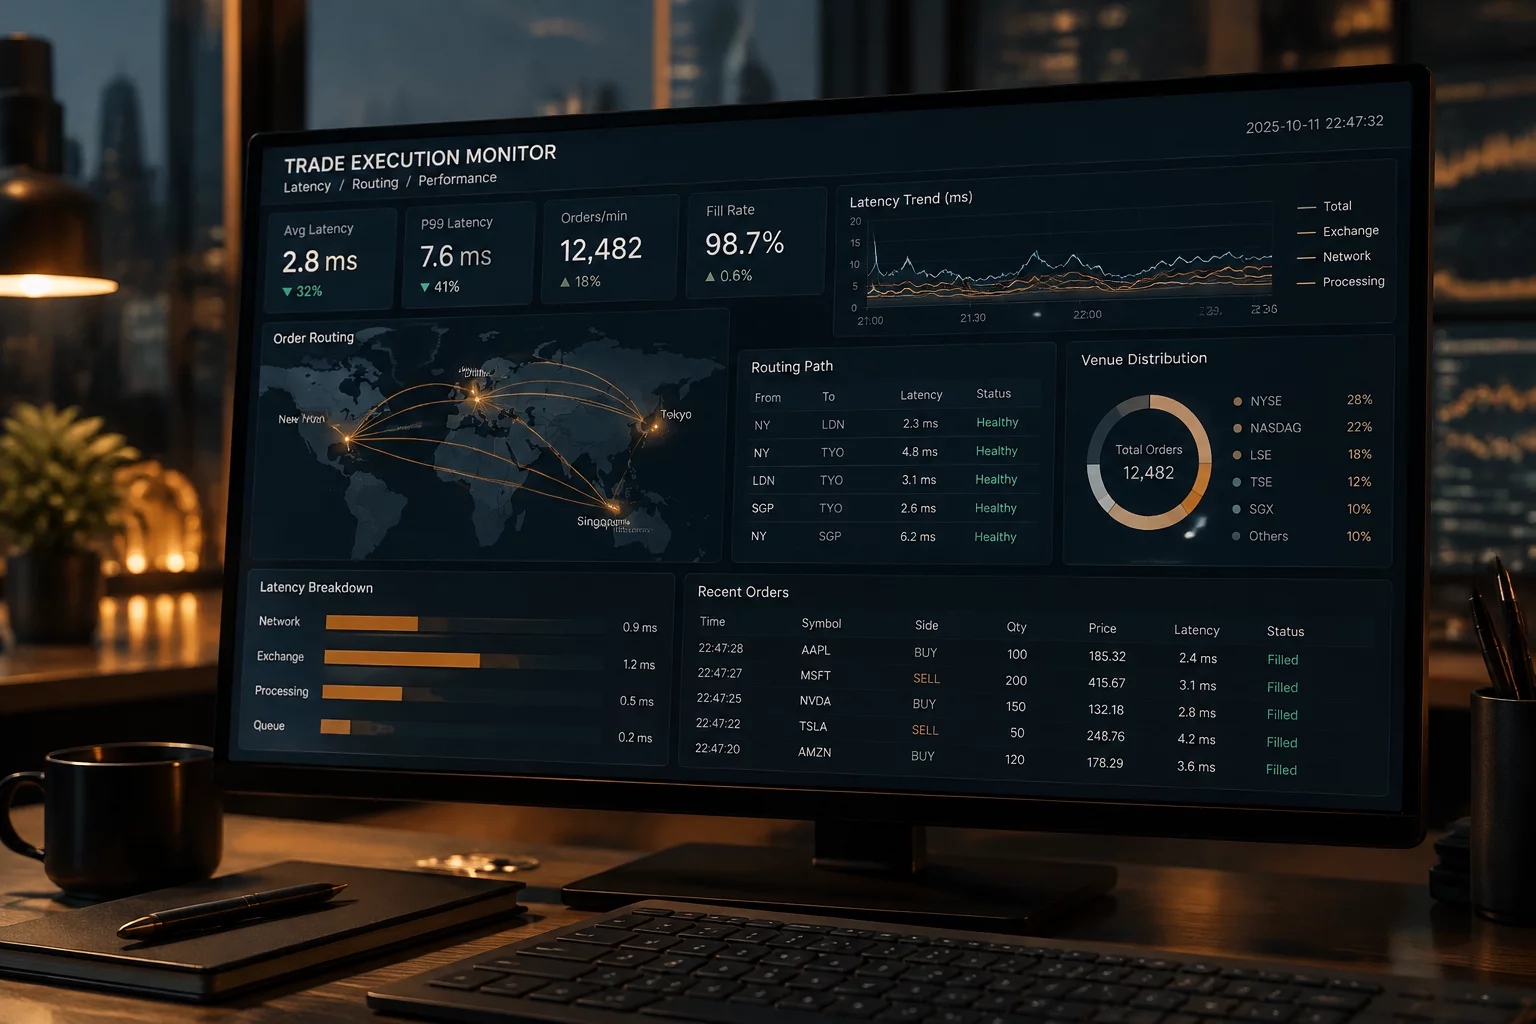
Fill Latency on Economic Release
Technical latency diagnostic interface highlighting millisecond slippage during macro releases.
Review Replay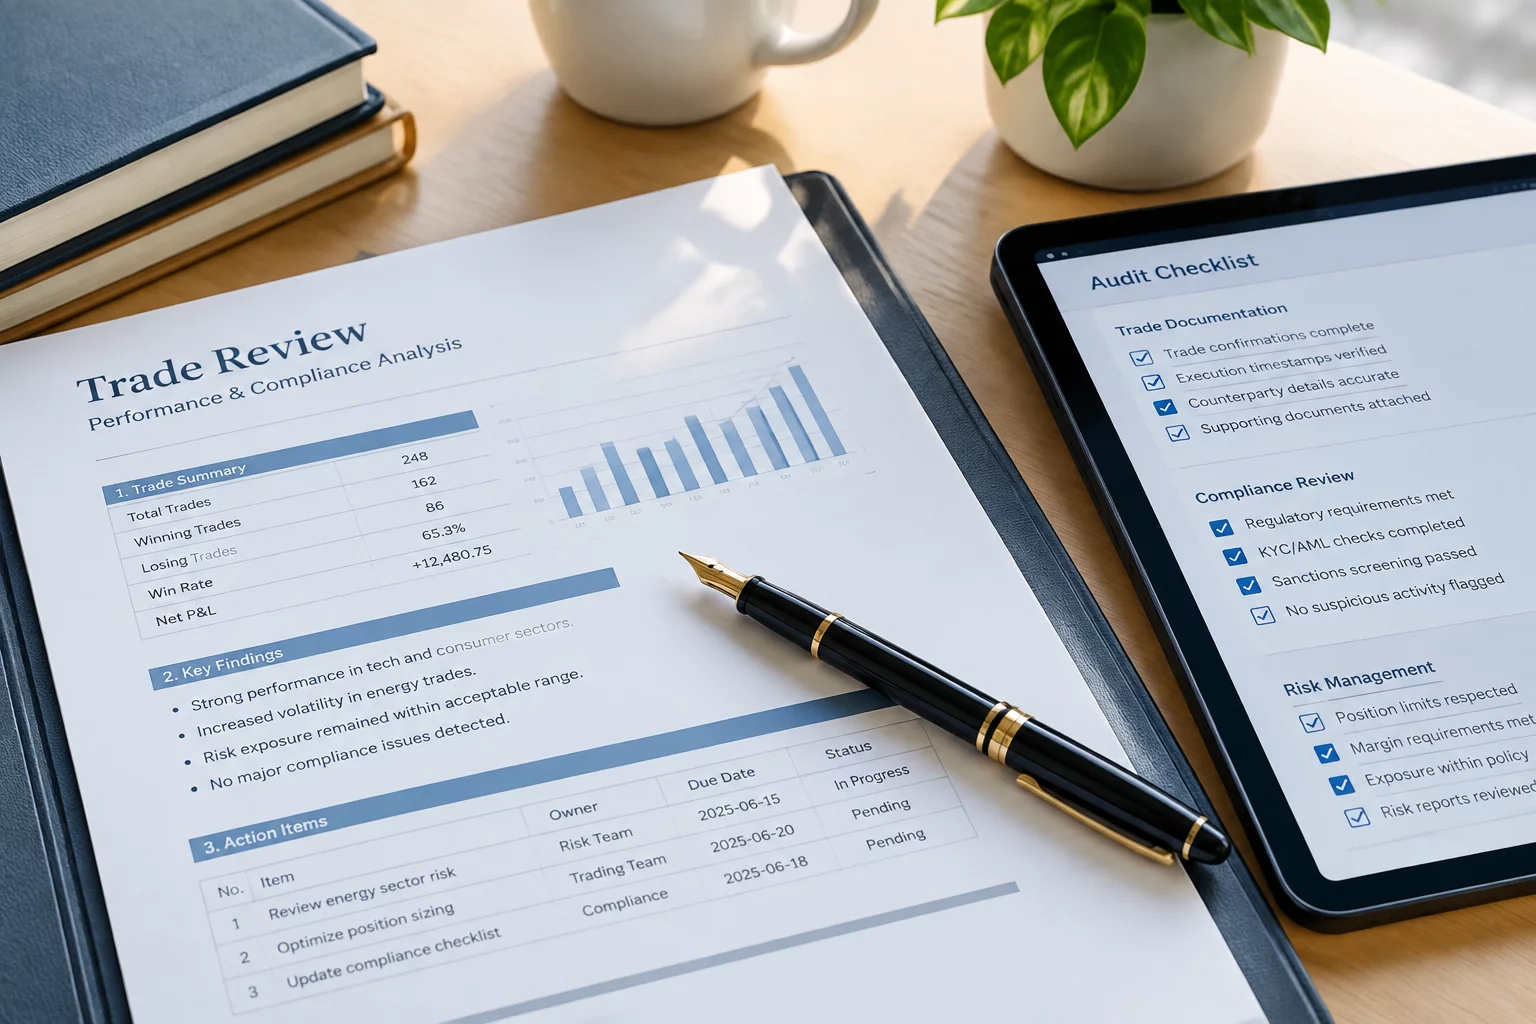
Limit Order Frictional Mismatch
Assessing synthetic queue position fallacies in thinly traded equity instruments.
Review Replay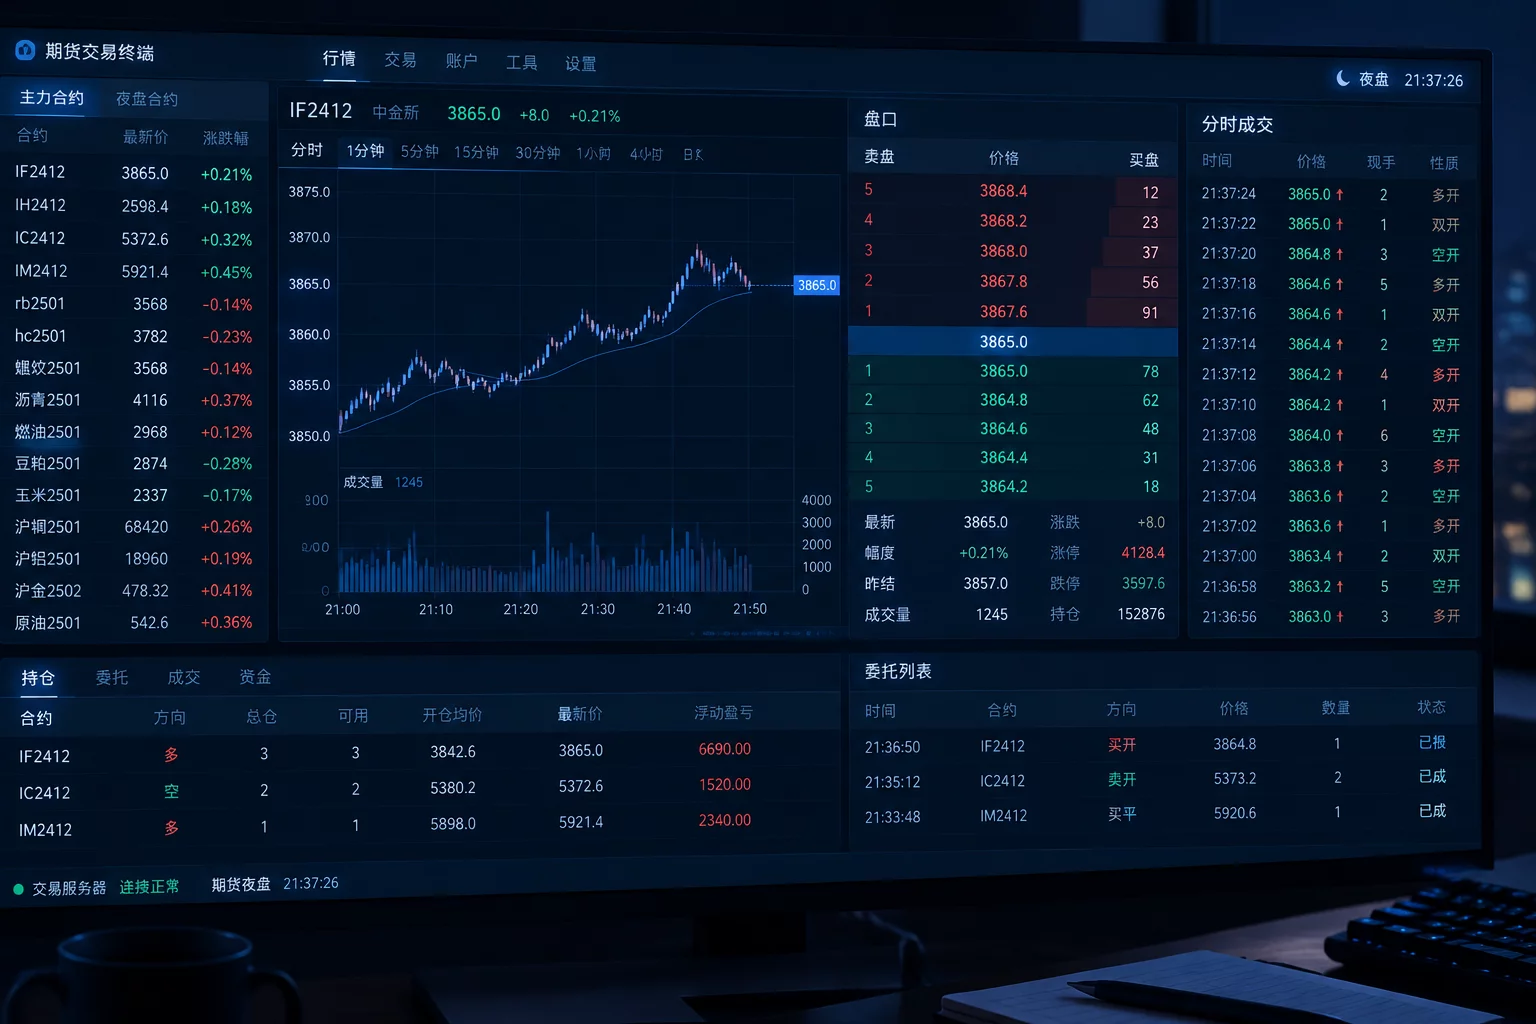
Bracket Liquidity Illusion
Evaluating automated bracket order executions under illiquid overnight futures conditions.
Review ReplayExplore Full Replay Archive
Access systematic execution post-mortems and friction audits across all market conditions.
Key Audit Takeaways
- Never rely on unadjusted simulated fill prices when compiling expectancy for momentum breakout strategies.
- Impose an empirical friction haircut of at least half the bid-ask spread during volatility expansion regimes.
- Always log the volume resting at top-of-book at trigger time to verify if the fill could have been absorbed in live matching.