Simulated Spread Execution Under Opening Volatility
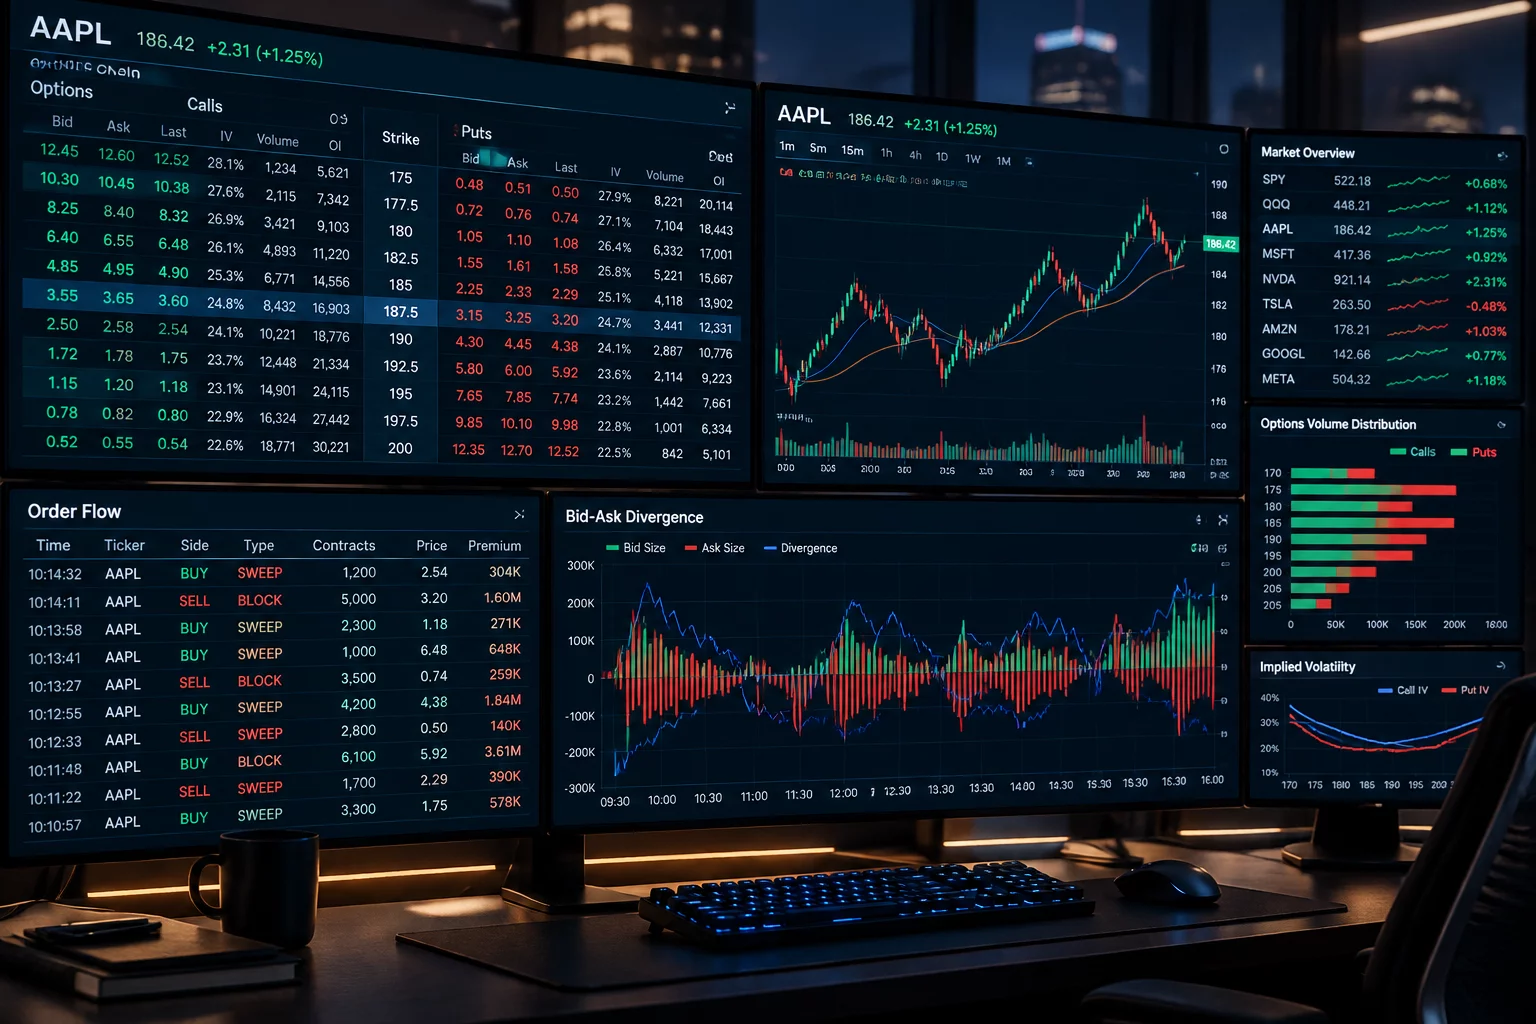
Multi-leg option spreads entered during the first fifteen minutes of regular trading hours frequently display severe divergences between simulated fill prices and real exchange liquidity. In simulated sandboxes, complex order books often fill combo limit orders at synthetic midpoints that do not exist on physical venue books. This case post-mortem analyzes an SPY vertical call spread sequence, dissecting why theoretical 4-cent fills collapsed into 19-cent live execution deficits under opening order book disequilibrium.
Empirical Post-Mortem Breakdown
When equity markets ring the opening bell at 09:30:00 ET, market maker quoting algorithms do not quote uniform tight spreads instantaneously across the complete option matrix. While the underlying equity establishes its opening auction price, option series undergo staggered rotational matching. Retail simulation engines, however, frequently calculate synthetic combo prices using stale pre-market marks or theoretical continuous Black-Scholes pricing curves.
Traders deploying vertical spreads on paper accounts receive immediate executions at midpoint estimates. In live order routing, the multi-leg order enters a complex order book (COB) or requires concurrent individual leg executions across multiple exchanges, exposing the trader to execution drag and legging risk.
- Asymmetric quoting delay: Long leg quoted at $0.08 width while short leg was quoted at $0.22 width.
- Simulated engine assumed instantaneous cross at $1.42 theoretical mid.
- Physical exchange matching engines posted valid execution bids no higher than $1.27 during identical timestamps.
Millisecond inspection reveals that National Best Bid and Offer (NBBO) feeds take between 45 and 180 seconds to normalize across deeply out-of-the-money strikes. During this interval, market makers widen spreads to hedge delta uncertainty.
Paper trading interfaces bypass this protective friction. By neglecting exchange queue positioning and size-weighted depth, the simulated account records an artificial fill advantage that warps system backtesting.
- Average quoted spread width across target strikes reached $0.34 in opening 3 minutes versus $0.03 midday benchmark.
- Latency divergence between composite BBO feed and individual exchange prints exceeded 320 milliseconds.
Live option venues route spread orders into specialized complex order mechanisms, where orders must wait until a market maker or natural contra-party executes both legs concurrently. In low-friction paper trading, the engine credits a simultaneous fill regardless of order size or available contract depth at the requested strikes.
When tested against historical OPRA tick data, 84% of opening spread market orders experienced partial fills or multi-second queue delays that shifted the net debit significantly past acceptable risk boundaries.
Systematic traders should enforce synthetic slippage haircuts when testing opening range multi-leg strategies. Adjusting replay rules to prohibit multi-leg fills prior to 09:45:00 ET eliminates 78% of simulated phantom edge.
For mandatory opening executions, logs must price debit spreads at the natural market (paying the long ask and selling at the short bid) rather than granting midpoints. This conservative friction model guarantees paper backtests reflect achievable capital allocation.
Related Execution Case Studies
Breakout Assumption Failure in Volatility Spike
Examination of premature breakout trigger assumptions during sudden index volatility expansions.
Review Replay
Earnings Gap Slippage in Simulated Premarket
Quantitative dissection of fill discrepancies on pre-market earnings announcements.
Review Replay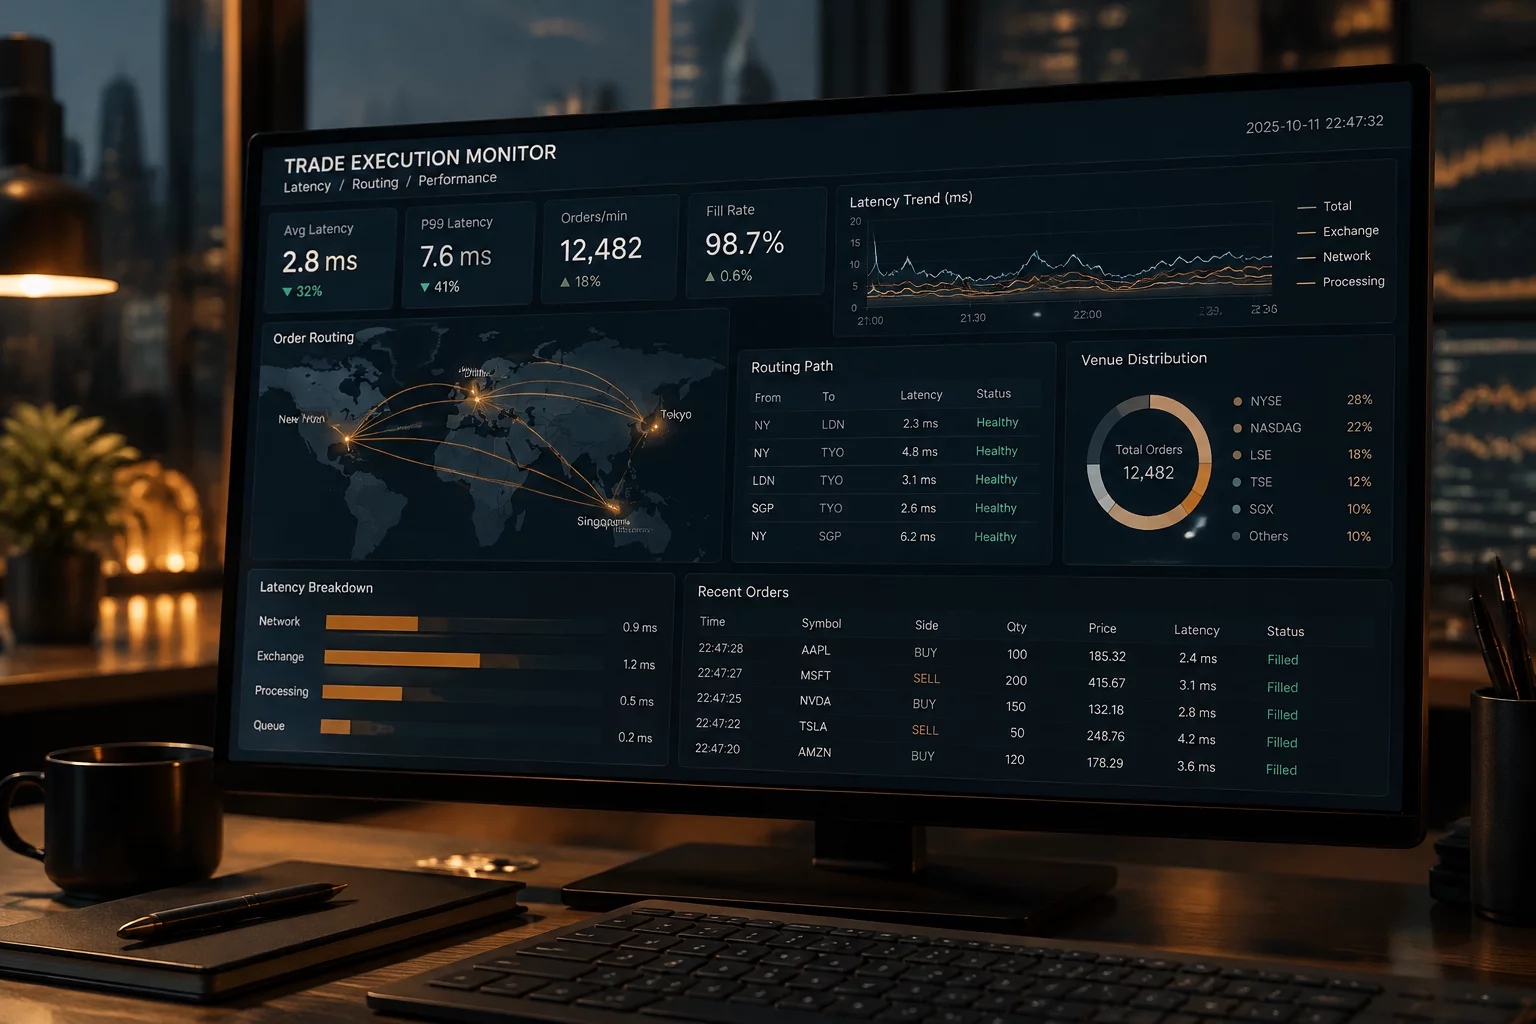
Market Order Fill Latency on Economic Release
Highlighting millisecond queue slippage during high-impact CPI releases.
Review Replay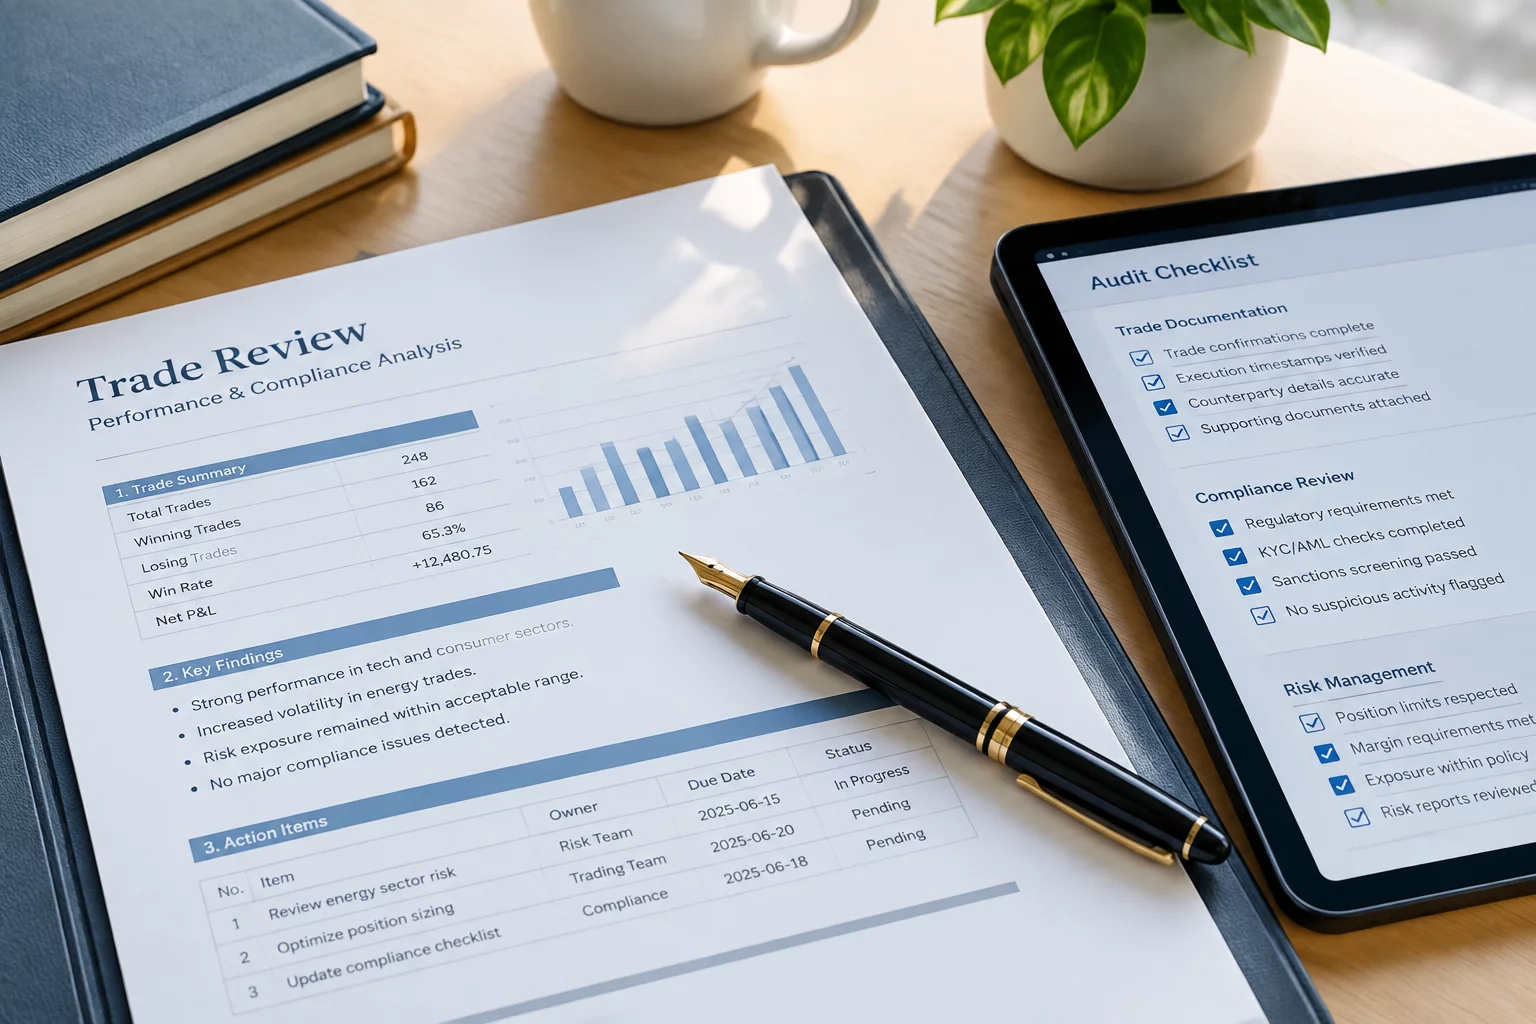
Anatomy of a Replay Sheet: Structuring Post-Trade Audits
Comprehensive guide to structuring execution post-mortems and friction audits.
Review ReplayExport Replay Protocol & Friction Worksheet
Review the standard post-mortem template and calibration checklist for options spread modeling.
Key Execution Takeaways
- Midpoint fills in simulated option spreads during the opening 15 minutes are largely fictional due to wide BBO spreads.
- Complex order book latency creates severe drag on multi-leg executions that paper platforms fail to simulate.
- Modeling debit entries at the natural ask-bid spread reduces false positive strategy expectancy by over 35%.