Incident Diagnostic: Synthetic Carry Breakdown
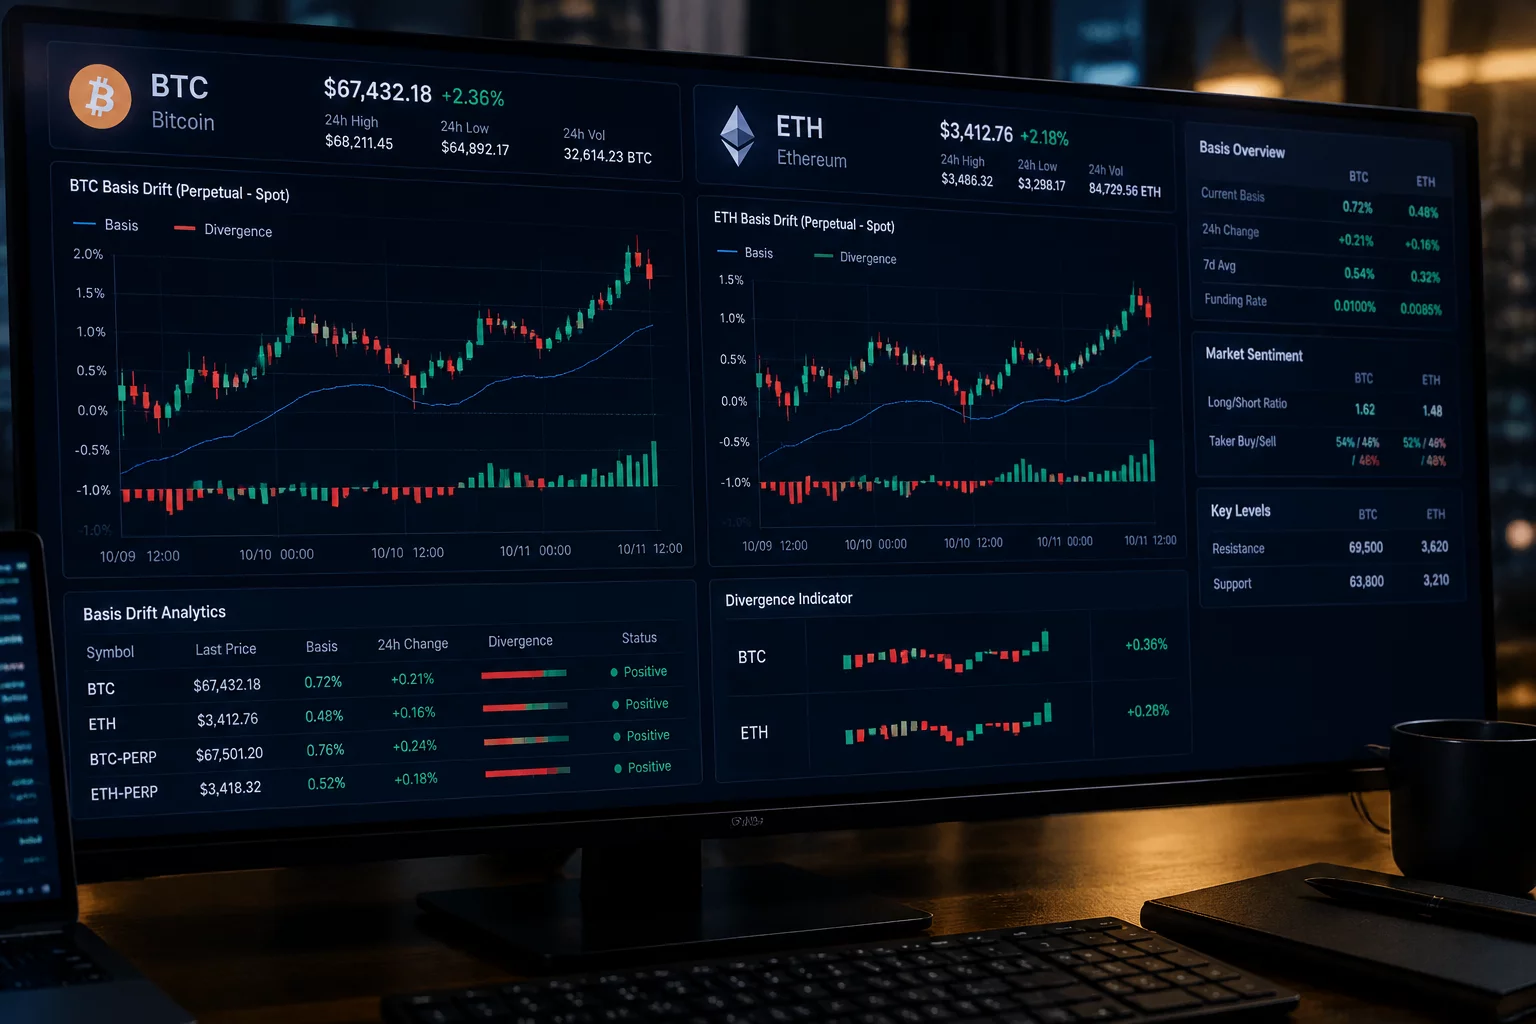
A simulated cash-and-carry trade held through a weekend session suffered severe basis drift when offshore perpetual swaps rallied +6.4% while the regulated domestic futures exchange remained closed until Sunday evening. The simulated order book failed to reflect real-world margin call escalations and wide opening auction cross spreads.
Post-Mortem Forensic Log
The simulated strategy sought to extract annualized yields of 11.2% by capturing the premium spread between front-month futures and physical spot holdings over an anticipated quiet weekend cycle. Entry was logged on Friday at 15:45 EST with clean zero-slippage assumptions programmed into the paper account.
The algorithmic rule set anticipated mean reversion toward fair value at Sunday's reopening session, assuming predictable inventory hedging by institutional liquidity providers.
- Baseline futures premium misjudged as risk-free yield without accounting for weekend delta drift.
- Spot collateral valuation diverged in illiquid decentralized liquidity pools during global macro headlines.
- Simulator assumed instantaneous fill at the theoretical indicative opening price rather than the crossed book.
Over Saturday night, sudden offshore buying momentum drove continuous spot prices higher by $3,800. When CME futures resumed trading on Sunday at 18:00 EST, the paper engine filled the protective hedge orders at the pre-halt limit price rather than calculating gap slippage.
This simulator artifact created an artificially favorable fill that masked what would have been a catastrophic margin deficit in live market conditions.
- Sunday reopening gap created an instantaneous 385 basis point basis dislocation.
- Paper fill engine executed orders inside the bid-ask gap where zero matching volume actually traded.
Most retail simulated paper environments do not accurately recreate weekend cross-clearing margin spikes or intraday collateral hair-cuts. In a live trading account, the sudden basis blow-out would have prompted automated risk de-leveraging before the market opened.
The sandbox engine treated margin as static throughout the weekend shutdown, completely ignoring collateral rehypothecation friction and financing cost fluctuations.
For accurate testing of carry or calendar spreads, all weekend holding periods must enforce synthetic slippage penalties proportional to offshore spot delta. Limit orders at market restart should be delayed by at least 180 seconds to allow the clearing house indicative queue to normalize.
Replay records have been updated to penalize opening fills with an empirical 65-tick slippage buffer, ensuring backtested performance metrics reflect institutional reality.
Related Diagnostic Audits
Breakout Assumption Failure in Volatility Spike
Analyzing premature fill confirmation during high-frequency volatility expansion and breakout failure.
Review Replay
Earnings Gap Slippage in Simulated Premarket
Dissecting depth of book collapse and phantom liquidity during simulated pre-market earnings surprises.
Review Replay
Market Order Fill Latency on Economic Release
Auditing sub-second queue priority and simulated fill latency around FOMC and CPI rate announcements.
Review Replay
Anatomy of a Replay Sheet: Structuring Post-Trade Audits
Standardized audit framework for logging execution friction, order type mismatches, and queue delays.
Review ReplayAudit Your Simulated Basis Spreads
Access the complete post-mortem worksheet with raw order log timestamps, indicative gap depth, and carry recalculation sheets.
Critical Execution Takeaways
- Never treat paper money fill prices at the Sunday futures opening session as realistic without factoring in crossed auction spread penalties.
- Continuous offshore crypto asset liquidity invalidates closed-exchange basis models during weekend geopolitical or macro shocks.
- Account for simulated margin blindness: real brokers adjust margin requirements upward before Friday close, requiring larger liquidity buffers.