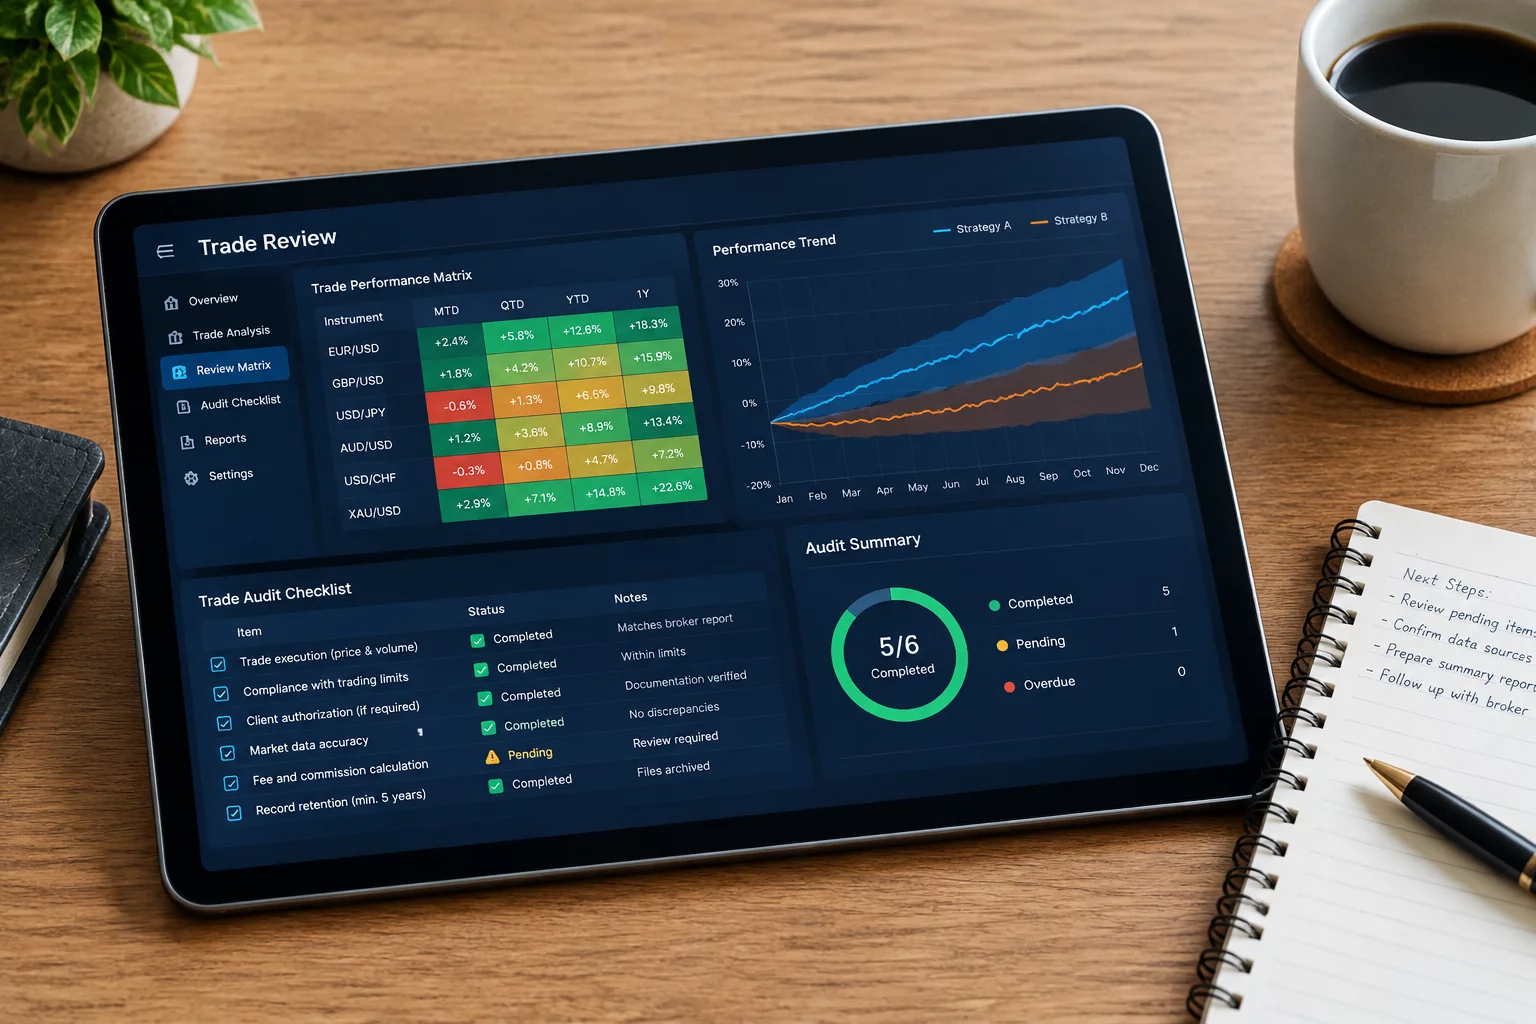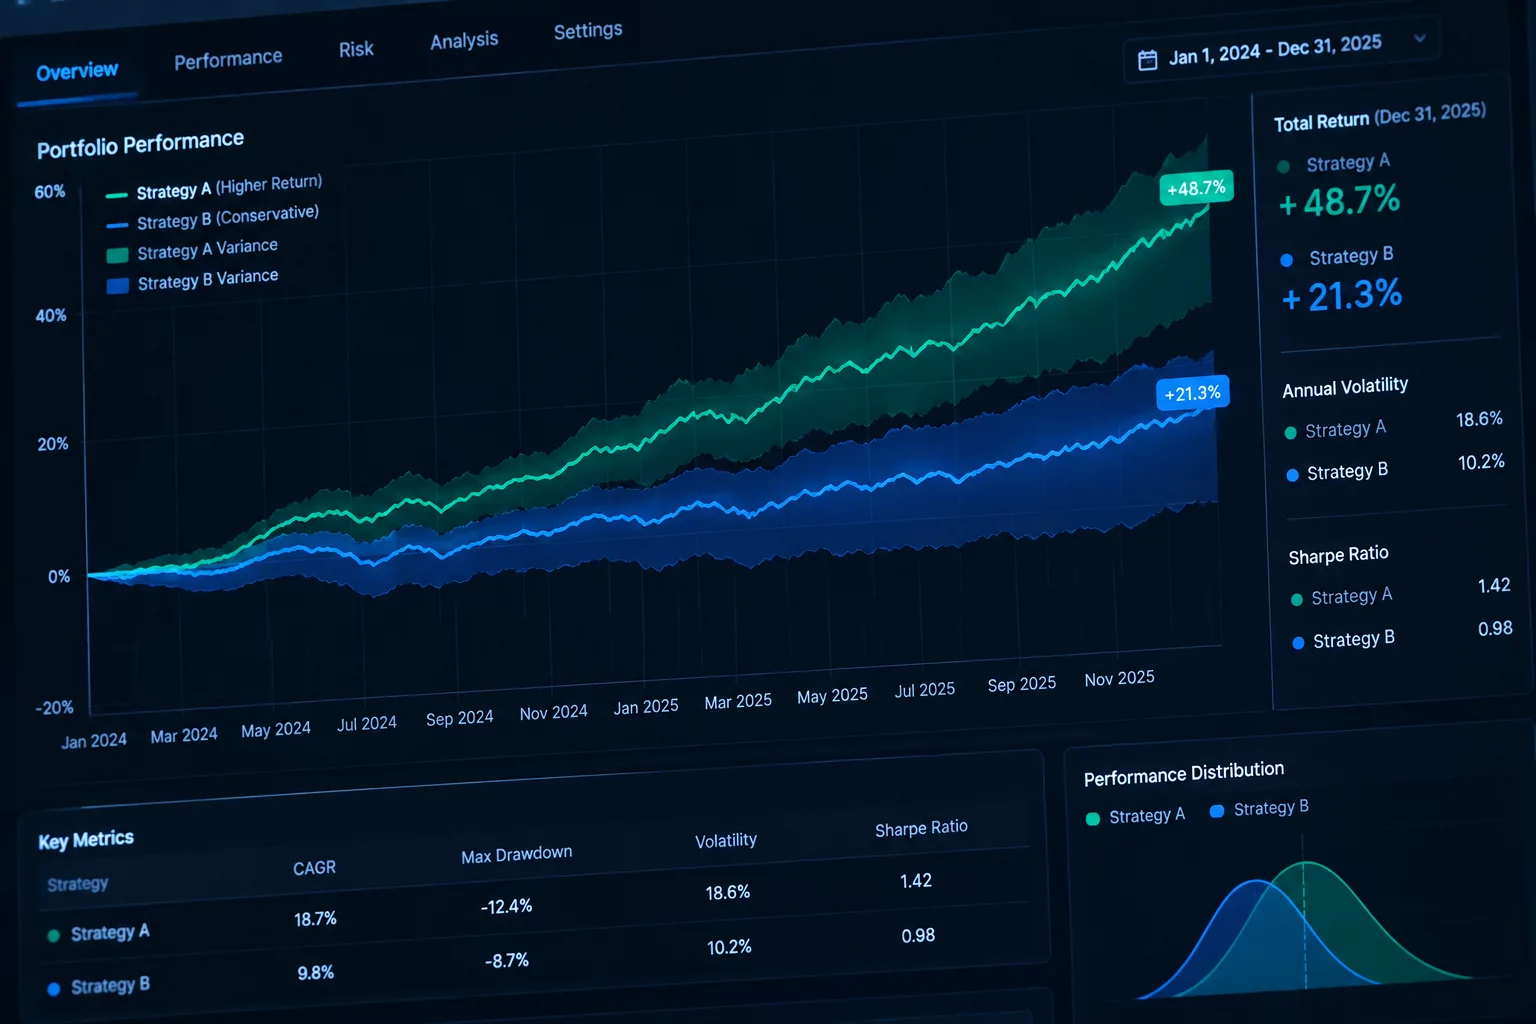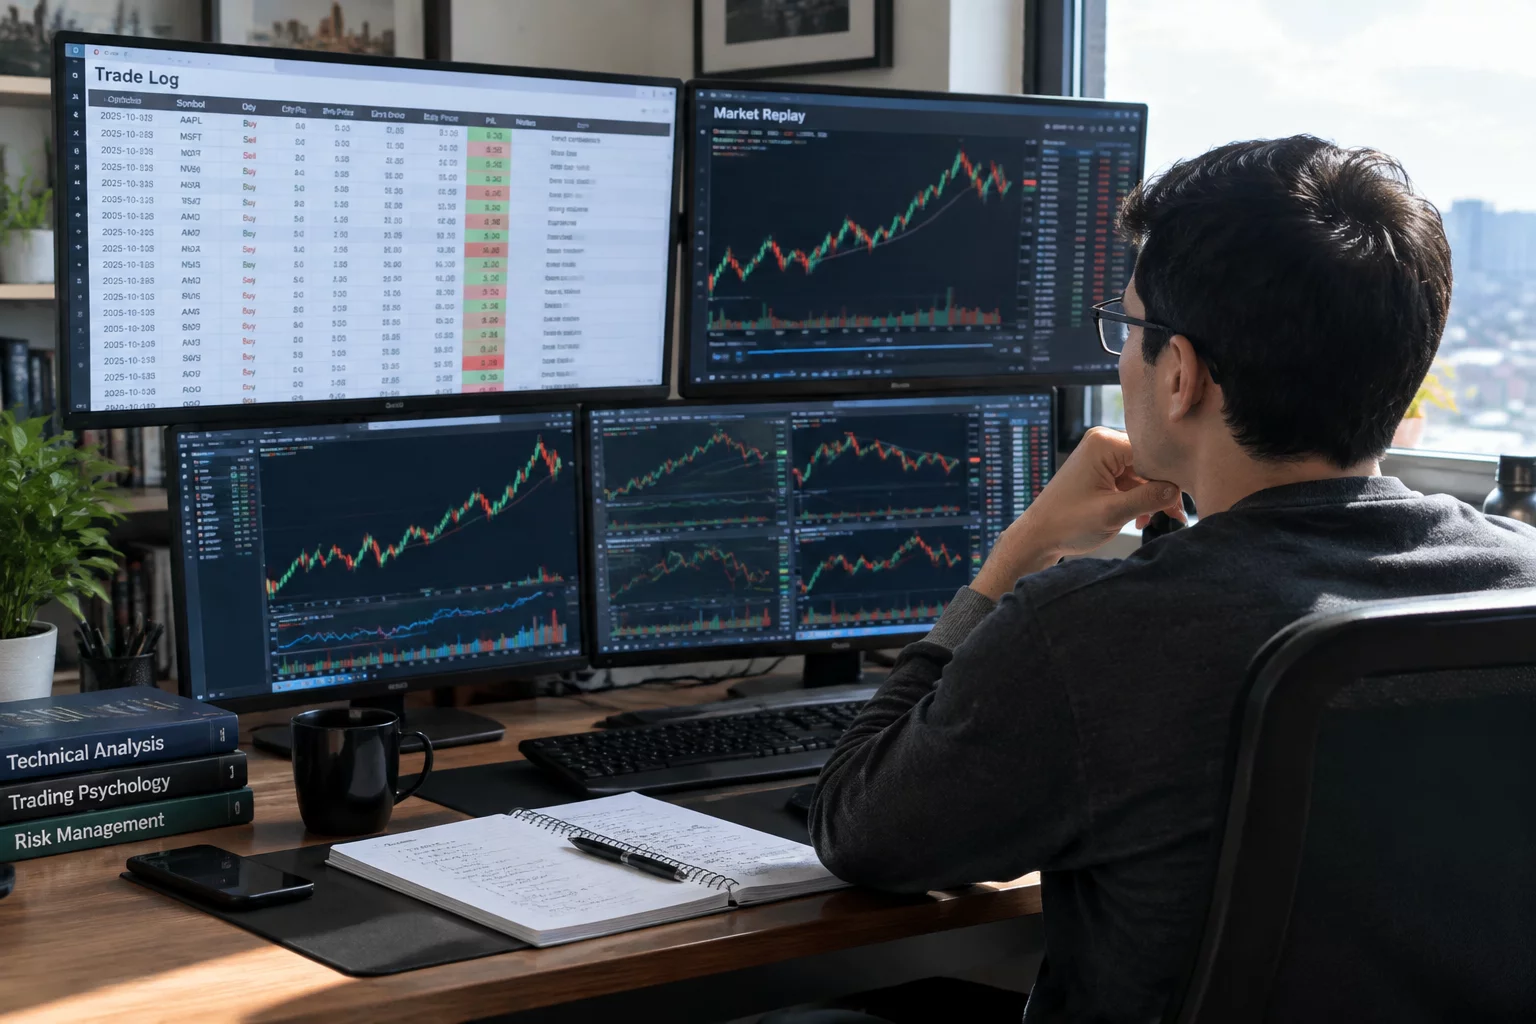
Analytical replay workstation displaying systematic weekly audit sheets, slippage discrepancy logs, and trade discipline matrices.
A methodical Friday review protocol designed to expose simulated fill illusions, document premise invalidations, and enforce systematic execution discipline.
Daily trade logs often capture immediate emotional reactions rather than statistically actionable operational tendencies.
A structured weekly review consolidates multi-day execution data into a cohesive post-mortem audit. By reconciling entry assumptions against fill queue dynamics across forty to sixty simulated transactions every Friday afternoon, practitioners differentiate genuine analytical edge from frictionless paper trading illusions.
| Audit Dimension | Target Threshold | Cadence Frequency |
|---|---|---|
| Fill Latency & Slip Penalty | ≤ 0.15% spread variance | Mandatory |
| Premise Invalidation Records | 100% stop logic documented | Non-Negotiable |
| Time-Stamped Depth Archives | Full Level 2 screenshot logs | Archived |
| Behavioral Rule Adherence | Zero unprompted position sizing | Weekly Metric |
Simulated trading environments create an artificial feeling of security because orders fill at favorable queue positions without real-market resistance. Without a scheduled cadence to audit these fills, operators develop habits that lead to severe drawdown when transitioning to live capital.
Conducting the post-mortem every Friday after market close locks in critical market memory before weekend decay sets in. The objective is not calculating net profit or celebrating winning runs, but stress-testing every recorded premise against actual historical depth.
Applying this systematic cadence transforms passive paper trading into institutional-grade execution development. Traders who consistently log and audit their weekly batches build an objective record of mechanical compliance that withstands real-world market turbulence.
Without an unyielding review rhythm, paper trading merely rewards reckless intuition with imaginary profits. The weekly checklist is where discipline becomes quantifiable.
— Elena Rostova, Senior Simulation Diagnostics Specialist
For active intraday traders logging 30 to 50 simulated executions per week, an exhaustive post-mortem requires approximately 90 to 120 minutes. Setting aside this dedicated block every Friday afternoon ensures market context remains sharp while removing daily stress.
Paper trading simulators frequently credit limit order fills the instant price touches the limit price, regardless of order volume ahead in queue. In your weekly checklist, penalize any fill that occurred on a single price touch without price trading completely through that level by at least one full tick.
The most prevalent flaw is Premise Invalidation Drift. Traders often enter with a strict technical thesis, but when price tests their stop level, they widen their risk parameter in simulation because no actual money is on the line. The weekly checklist immediately catches this discrepancy.
Compare your paper trading metrics against live liquidity constraints with our diagnostic replay sheets and analytical case studies.